NEW YORK–OnePay, a Walmart-backed financial technology company, has launched banking services for youth ages 13 to 17 that include savings, checking access, investing and a card intended to help build credit history.
Parents can add teens as authorized users on their checking accounts and give them access to OnePay Invest with parental oversight, the company said in a Sept. 21 news release. Teens can set savings goals and earn a 3.35% annual percentage yield, according to OnePay. The company also offers a personalized card design.
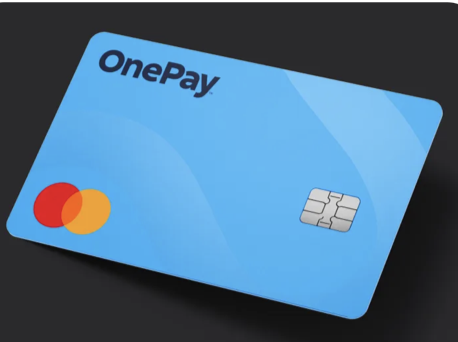
OnePay said its Builder Card is intended to give teens an early start on credit history. Its One to One feature allows family members to transfer money instantly at no charge. Parents can set spending limits and card controls, the company said.
The Stated Goal
The company’s stated goal is for young people to reach age 18 with a 700-credit score, $1,000 in savings and five years of investing experience. Those figures are an ambition, not a promised outcome.
“A lot of people turn 18 with no credit history, next to no savings, and no idea how to invest or what to invest in,” OnePay general manager Harsh Gupta said in the release.
When teens turn 18, they can open their own OnePay accounts and retain their money, investments and rewards, the company said.