WASHINGTON — The Defense Credit Union Council has asked the National Credit Union Administration to consider whether people named as beneficiaries on members’ share accounts could qualify for credit union membership while the members are still alive.
Separately, DCUC has also introduced digital ads backing several congressional candidates.
Under the proposal, a living person validly designated as a beneficiary on a member share account, including a payable-on-death or in-trust-for account, would become eligible when the designation is made. Eligibility would continue after the member’s death without a separate deadline to join, DCUC said.
“Receiving an inheritance and qualifying for credit union membership are not the same question,” said Anthony Hernandez, DCUC’s president and CEO. “We are asking that the NCUA examine what that distinction means for a survivor managing grief, paperwork, and financial decisions and whether eligibility could be established while the member is still alive.”
Whom Proposal Would Cover
The proposal could cover nieces, nephews, unmarried partners, caregivers and close friends who do not otherwise qualify through family, household, employment, association or geographic ties. DCUC wants the NCUA to examine its application across federal credit union charter types and said comparable provisions for state-chartered credit unions could be considered through state systems.
The NCUA’s current Chartering and Field of Membership Manual recognizes immediate-family and household relationships, as well as spouses of people who died within a credit union’s field of membership. It does not provide a universal membership pathway based on beneficiary status, DCUC said. The council’s request concerns beneficiaries who have not joined a credit union and have no other qualifying connection.
Membership Would Remain Voluntary
The designation would establish eligibility, not enroll the beneficiary or give them access to the member’s account, DCUC said. It also would not accelerate payment of inherited funds.
“The concept would create eligibility, not automatic membership,” said Jason Stverak, DCUC’s chief advocacy officer. “A beneficiary would still decide whether to join, complete the required checks, and remain free to move the money elsewhere.”
Those who chose to join would still have to meet ordinary admission, identification, disclosure and opening-share requirements. Bank Secrecy Act, sanctions, fraud-prevention and estate-settlement controls would remain in place, according to the council.
DCUC asked the NCUA to determine whether it could implement the full proposal under existing law and identify any provisions that would require congressional action. It also asked the agency to examine how a rule would address revoked or changed designations, contingent beneficiaries, minors, closed accounts, record retention, privacy and accessible ways to enroll.
Other Recommendations
The review should weigh possible reductions in repeated eligibility paperwork and opportunities for advance planning against implementation costs, fraud risks and effects on existing membership boundaries, DCUC said. Retaining deposits would be a possible result if beneficiaries chose to join, the council said but would not be a condition of receiving inherited funds.
DCUC requested a meeting with NCUA Chairman John Crews and agency staff responsible for legal, chartering and consumer-protection matters. It offered to provide anonymized operational examples and to discuss the proposal with other trade associations and state-system representatives.
Digital Ads Back Candidates
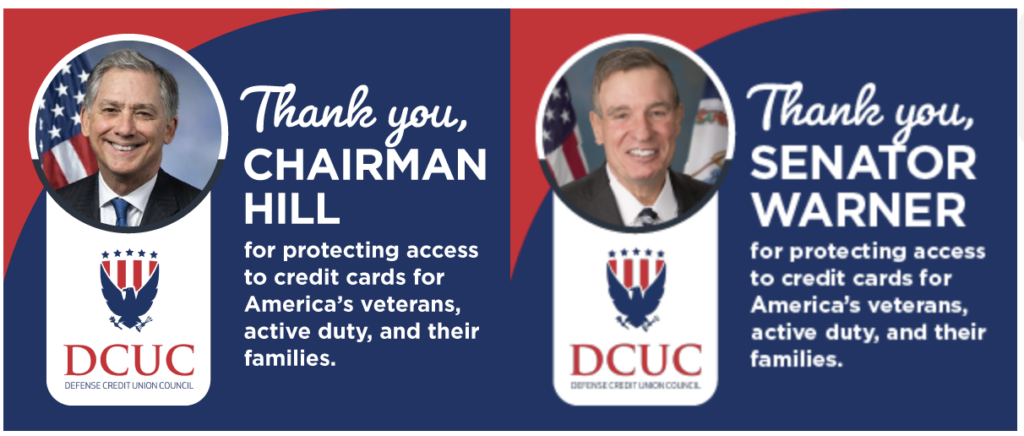
Separately, DCUC is running digital ads in Arkansas, Virginia and the Washington, D.C., area recognizing U.S. Sen. Mark Warner and U.S. Rep. French Hill for their engagement on policies affecting credit unions and the financial services used by servicemembers, veterans and military families.
The ads, funded by DCUC’s Defending Credit Unions National Advocacy Fund, thank Warner, a Virginia Democrat, and Hill, an Arkansas Republican, for “protecting access to credit cards for America’s veterans, active-duty, and their families,” according to the council.
The campaign comes as DCUC opposes proposals that would impose government-mandated routing requirements, caps or other restrictions on interchange revenue. The council says interchange revenue helps credit unions pay for secure payment systems, fraud prevention, cybersecurity, member rewards, low- or no-fee products and financial counseling.
“We appreciate Sen. Warner and Congressman Hill for their engagement on issues that directly affect credit unions and the military and veteran communities we serve,” DCUC President and CEO Anthony Hernandez said in a statement. He said policymakers should consider how changes to the payments system could affect the people who rely on defense credit unions.
‘Unexpected Challenges’
DCUC said those credit unions serve members across state lines, on military installations, during deployments and overseas. Servicemembers and their families need reliable access to accounts and payment services as they relocate, change duty stations or face unexpected financial challenges, the council said.
“Financial readiness depends on reliable access to financial services,” said Jason Stverak, DCUC’s chief advocacy officer. He said the council would continue working with policymakers to support competition and consumer choice while preserving credit unions’ ability to invest in security and services for military families.