
DETROIT — More homebuyers younger than 35 are relying on older co-applicants to secure mortgages as high home prices and borrowing costs strain affordability, according to an analysis of public mortgage data by Rocket.
The share of buyers under 35 purchasing homes with a co-applicant older than 55 increased 21% from 2018 to 2025, the analysis found. About 3.3% of transactions involving younger buyers — roughly one in 30 — now include an older co-applicant, who may be a parent or another relative, Yahoo Finance reported.
The trend comes as younger buyers retreat from the housing market. Home purchases among those under 35 fell 15% over the same period, while purchases involving older co-applicants edged higher, according to the report.
How Co-Applicants Help
A co-applicant applies for a mortgage alongside the primary borrower, allowing lenders to consider both applicants’ income, assets and credit histories. Unlike a co-signer, who generally does not receive an ownership stake and agrees to pay if the borrower defaults, a co-applicant typically shares ownership and responsibility for mortgage payments, Yahoo Finance explained.
Where Older Co-Applicants are Most Common
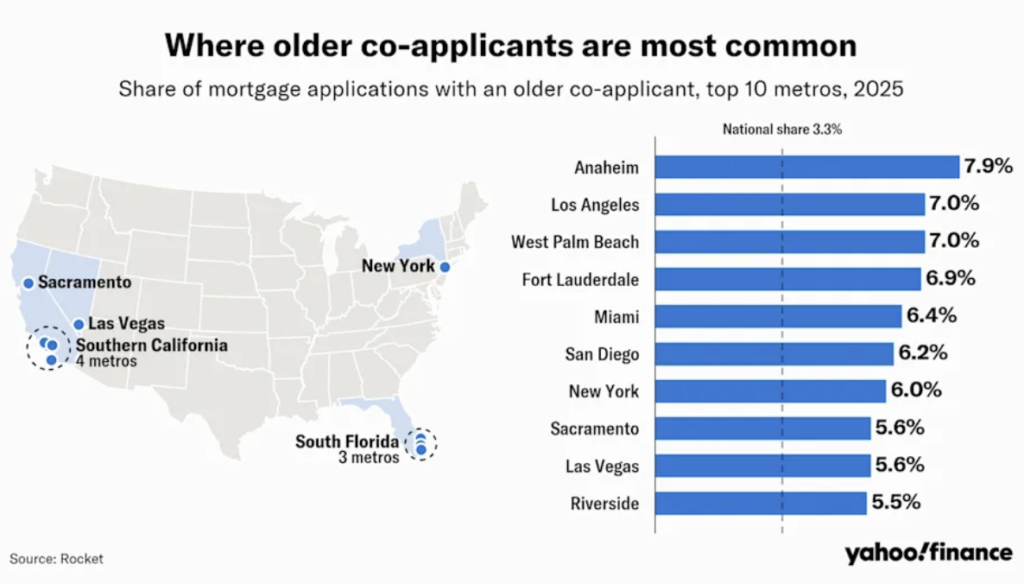
The practice is more common in expensive housing markets, according to the Rocket analysis cited by Yahoo Finance:
- Anaheim, California: Nearly 8% of younger buyers had an older co-applicant; the city’s median home price approaches $1 million.
- Los Angeles, San Diego, South Florida and New York: Older co-applicants also were relatively common.
- Milwaukee: 2.3% of younger buyers had an older co-applicant.
- St. Louis: 2.4% of younger buyers relied on an older co-applicant.