
WASHINGTON — U.S. banks tightened lending standards for small businesses, commercial real estate borrowers and some households in the third quarter as concerns about the economy grew, according to a new Federal Reserve survey.
The Fed’s October Senior Loan Officer Opinion Survey (SLOOS) on Bank Lending Practices, released Nov. 2, showed an uneven credit picture, with smaller businesses, riskier borrowers and commercial property facing particular pressure.
The quarterly survey included responses from 61 domestic banks and 18 U.S. branches of foreign banks. It measures lenders’ reported changes in standards, terms and demand, rather than actual loan volumes.
Standards for commercial and industrial loans to large and middle-market companies were broadly unchanged from the previous survey, while banks tightened standards for smaller businesses, CNBC reported.
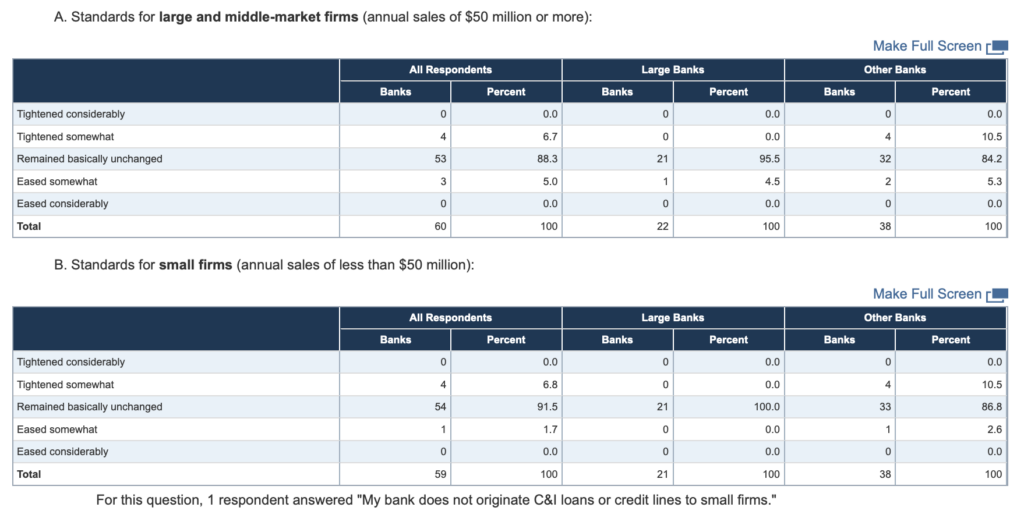
Higher Premiums on Riskier Business
Banks also reported higher premiums on riskier business loans across firms of all sizes. Lenders cited a less favorable or more uncertain economic outlook and worsening problems in specific industries.
Commercial real estate faced tighter standards across construction and land development loans, nonfarm nonresidential properties and multifamily properties. Banks reported weaker demand in all commercial real estate loan categories, according to CNBC’s account of the survey.
Lenders also tightened standards for nonbank financial institutions, including private equity funds and business and mortgage credit intermediaries. The pullback came as private equity funds and business credit intermediaries sought more liquidity.
Banks cited economic uncertainty and concerns about the weakening financial condition of nonbank borrowers, CNBC reported.
Household Lending Conditions are Mixed
Household lending conditions were mixed. Mortgage standards were broadly unchanged, with some easing for jumbo mortgages and tighter standards for subprime loans. Banks reported weaker demand across all residential real estate loan categories.
Credit card approvals increasingly favored borrowers with stronger credit. Banks reported being more likely to approve applications from prime and super-prime borrowers and less likely to approve subprime applicants, with small banks driving the subprime trend, according to the survey.
The tighter credit conditions followed a sharp rise in borrowing costs during the third quarter, CNBC reported. The yield on the 10-year Treasury note reached an intraday high of 5.349% on Oct. 5, its highest level since April 2002, amid concerns about rising U.S. debt.
‘Broader Repricing’
Tiffany Wilding, a managing director and economist at PIMCO, said small businesses, housing and heavily indebted companies face tighter credit and higher borrowing costs as the artificial intelligence investment boom squeezes other parts of the economy.
“Higher government bond yields have catalyzed a broader repricing of credit risk, especially for lower-quality borrowers,” Wilding wrote in an Oct. 28 note cited by CNBC.
The lending survey’s signs of stress among riskier households follow a CNBC and SurveyMonkey poll that found one in five Americans who rent or have a mortgage spend at least half their pretax income on housing. Another 49% spend between 25% and 49%. CNBC said lender guidelines generally recommend spending 28% to 30% of income on housing.
A separate Fed report also pointed to growing repayment difficulties. The Survey of Consumer Finances, released Oct. 9, found that nearly 20% of families were behind on loan payments at the end of 2025, up from about 12% in the previous survey in 2022, CNBC reported.