
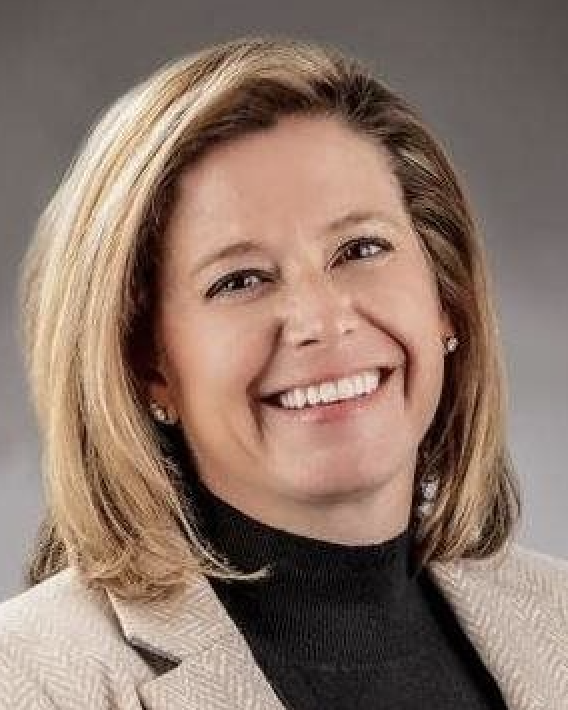
COLUMBUS, Ohio—As groundbreaking new payment and AI technologies hit the market almost daily, credit unions are feeling the pressure to adopt quickly or fall behinds. But one person is cautioning that a disciplined, careful approach is the smarter choice in 2027—while also sharing some other things CU leaders should be thinking about.
Christine Mayes, EVP and chief member engagement and payment solutions officer at Corporate One Federal Credit Union, says that just like natural-person credit unions, “healthy growth” for her organization hinges on deep relationships with members. At that means that before widely deploying or recommending new technologies like digital assets and AI, Corporate One has been reviewing use cases and evidence to assess their potential value for credit unions and their members.
The organization understands that an overly hasty embrace or any innovation or new offering can undermine its most valuable asset: member trust, Mayes stated.
Mayes provided her insights as part of the CU Daily’s series, “The Growth Imperative,” which is focusing on strategic planning for 2027.
Her thoughts appear below.
The CU Daily: Has the role of the corporate credit union changed? If so, how?
Mayes: Yes, the role of a corporate as a “credit union for credit unions” has evolved, but the mission remains the same: helping credit unions succeed. Credit unions still rely on Corporate One for the core services that have always been essential, including payments, investments, funding, and liquidity management.
What’s changed is the environment credit unions operate in. Technology is advancing rapidly, member expectations continue to rise, and the pace of change across the financial services industry is accelerating. Today, we’re helping credit unions navigate change, connect to new payment capabilities, evaluate emerging opportunities, and prepare for the future. Just as importantly, we help credit unions benefit from the power of cooperative scale by aggregating resources, expertise, and demand in ways that create access to capabilities many institutions could not efficiently build on their own.
Our immediate payments solutions and multi-seller securitization program are good examples of this approach. By bringing credit unions together, we can create efficiencies, expand access, and deliver value that extends well beyond what any one institution could achieve independently. We also play an important role as an advocate for the credit union system, helping share the power of the cooperative movement and ensuring credit unions have a seat at the table on impactful issues.
Ultimately, we see our role as helping credit unions remain focused on serving their members while we provide expertise, solutions, and scale that enable them to compete and thrive in a rapidly evolving marketplace.
The CU Daily: Is growth a priority for Corporate One in 2027? If so, what type of growth in particular?
Mayes: Growth is a clear strategic priority for Corporate One, but we are not pursuing growth for growth’s sake. We are pursuing purposeful, disciplined growth that strengthens our organization and creates lasting value for our members. As we work toward becoming a $10 billion-plus institution by 2030, our 2027, priorities include expanding immediate payments and maturing send capabilities, deepening investment and funding relationships, growing adoption of our settlement and cash management solutions, and creating more durable, multifaceted member relationships.
At the same time, we are modernizing our platforms, automating processes, and strengthening our data capabilities so we can scale efficiently without allowing cost and complexity to grow at the same pace. Ultimately, we’ll measure growth not only by size, but by our ability to invest in innovation, expand member value, and help credit unions remain strong, relevant financial partners for the future.
The CU Daily: What is misunderstood about growth? What do you consider the most important growth metric to watch?
Mayes: Growth is often misunderstood as simply getting bigger, whether measured by assets, revenue, or new members. While those measures matter, they do not tell us whether growth is sustainable, strategically aligned, or creating meaningful long-term value.
For Corporate One, healthy growth must accomplish three things:
- Deliver measurable value to our member credit unions
- Strengthen our financial position and capacity to invest
- Build durable relationships that extend beyond temporary or rate-sensitive activity.
Because our balance sheet can fluctuate with economic conditions, liquidity, and interest rates, the most important measure is the depth and durability of our member relationships. By evaluating how members engage with us across payments, settlement, investments, and funding solutions, we can make more informed decisions about strategy, capital deployment, and resource allocation while ensuring our growth strengthens both Corporate One and the credit unions we serve.
The CU Daily: What direction do you provide to members—or what direction has been sought—about stablecoins and tokenization? What are the focus and message of those conversations?
Mayes: Corporate One has invested significant time evaluating stablecoins, tokenization, and the broader digital asset landscape. We have an established internal working group that monitors regulatory guidance and considers the potential implications and opportunities for our organization and our members. We are listening closely to credit unions and participating in industry workgroups to help ensure the credit union system can engage with emerging digital assets safely, compliantly, and on equal footing with other financial institutions.
We are mindful that many of the regulatory and market questions are still being answered. As a result, we have focused on understanding the opportunities, risks, and potential implications for credit unions. We will soon move beyond research and into practical learning. Over the next year, we plan to evaluate and participate in a disciplined proof of concept to better understand the technology, operational requirements, governance considerations, and partner ecosystem needed to support future digital asset capabilities.
The objective is not to launch a product, but to build the knowledge and readiness necessary to act quickly when regulatory clarity and compelling member use cases emerge. In our conversations with members, we encourage a similar approach: understand the technology, focus on real-world applications rather than market speculation, and be prepared to make informed strategic decisions as the landscape develops.
The CU Daily: How have you used AI this year? How has it evolved? How do you foresee both your organization and your member credit unions using AI in 2027?
Mayes: Over the past year, Corporate One’s use of AI has evolved from experimenting with individual productivity tools to building a more strategic, enterprise-wide capability. We are using AI to improve employee productivity, unlock institutional knowledge, enhance cash forecasting, and accelerate software development, all within a framework of strong governance, security, and responsible data practices. In 2027,
I expect both Corporate One and our member credit unions to embed AI more deeply into everyday business processes, from member service and fraud detection to decision support and operational automation. Ultimately, the differentiator will not be who has access to AI, but who can use it responsibly to deliver measurable value while maintaining security, compliance, and member trust.
The CU Daily: For credit unions looking to do their own monitoring, how do you monitor what’s taking place in the fintech space?
Mayes: We monitor fintech developments through direct investment, strategic partnerships, and active industry engagement. Our investments in CUSOs such as TranzCapture, Primary Financial, ModernFI, CU Capital Management, eDOC Innovations, CURIO, and Tru Treasury give us valuable insight into emerging technologies and evolving credit union needs.
We also have fintech partnerships that provide specialized capabilities behind our Immediate Payments Hub, allowing us to innovate while remaining focused on a secure, integrated member experience. In addition, our experts regularly attend industry events and conferences to engage with CUSOs, fintechs, and other leaders, and our participation in Circuit connects us to a collaborative innovation network that brings together research, emerging technology, and strategic partnerships.
This multifaceted approach helps us move beyond simply tracking trends to identifying, testing, and advancing solutions that deliver practical value to credit unions.
The CU Daily: Where have you found room to squeeze out costs?
Mayes: Corporate One has found meaningful opportunities to reduce costs by taking greater control of our technology and expanding automation across the organization. A prime example is our Direct Connect initiative, which established our own connections to the RTP network and FedNow Service and allowed us to stop using an outside vendor for this connection.
Direct Connect also enabled us to transition members to a new Payments Research Portal. Beyond improving our cost structure, the project has streamlined member onboarding and reduced member support cases, allowing our teams to focus less on access and system friction and more on strategic support, education, and proactive outreach. Looking ahead, we are exploring additional automation opportunities to scale efficiently, increase organizational capacity, and limit incremental costs as our payments business and member relationships grow.
The CU Daily: Where will your focus be in 2027?
Mayes: Over the past several years, Corporate One has delivered record financial performance, expanded our membership base, and invested in modernizing our technology foundation.
In 2027, we’ll build on that momentum by completing key elements of our modernization strategy and turning those investments into enhanced value for credit unions. That includes expanding our Hub Strategy toward a more comprehensive Payments Hub that includes legacy payment capabilities, and bringing the same modern approach to investments and funding.
By creating a more integrated technology environment, we’ll be better positioned to deliver solutions that are easier to access, easier to use, and designed around how credit unions operate today. Just as importantly, we’ll continue to provide the liquidity, investment, and financial strength our members rely on while pursuing disciplined growth opportunities that create long-term value. Our goal is to remain a trusted partner today while building the capabilities credit unions will need tomorrow.
The CU Daily: Are you doing or planning anything else that deserves special attention?
Mayes: One initiative that deserves special attention is the continued expansion of our Immediate Payments Hub. More than simply a connection to the RTP network and FedNow Service, the hub is an open, core-agnostic ecosystem that brings receiving, sending, transaction processing, settlement, funding, and liquidity management together through Corporate One.
By integrating with core processors, digital banking providers, and fintechs through standardized APIs, the hub gives credit unions the flexibility to select the partners and capabilities that best align with their strategic goals while avoiding unnecessary complexity and fragmentation. In doing so, credit unions can reduce vendor relationships, lower costs, and improve operational efficiency.
The hub also provides centralized visibility across both immediate payment rails, simplifying research, reporting, reconciliation, and day-to-day operations. Most importantly, it is designed to evolve alongside our members. Credit unions can easily add new use cases, strengthen fraud prevention efforts, enhance member experiences, and expand their immediate payments strategies, all with support from our certified specialists.
Ultimately, the Immediate Payments Hub marks a significant step toward making immediate payments simpler, more scalable, and more accessible for credit unions.
–Reporting by Anne Battle Schultz
Additional Resources
Other articles that are part of this series include:
- As CUs Plot Plans for Growing in 2027, One Person Urges Them Not to Overlook the Unicorns
- In Planning for 2027, Don’t Overlook the Value of a Clear, Consistent Brand: A CU Daily Series
- Two Paths to Growth in 2027 & What Should be on the 2027 Planning Agenda: A CU Daily Series
- As CUs Prepare 2027 Strategic Plans, a Reminder of the Value of Offering PMI
- The Members to be Targeting in 2027–And How to Know Who They Are: A CU Daily Series