WASHINGTON–Despite all the money and time credit unions have invested in Washington and Congress, the nation’s financial cooperatives continue to find themselves often left outside looking in when it comes to provisions included in legislation that seek to help community banks, with the CLARITY Act the latest such example.
The Senate is scheduled to vote today on the digital assets legislation that has the backing of credit union trade groups. But in the latest revisions to the bill released late on Sunday night, there is language that provides for some protections for banks and community banks of $10 billion in assets and below should the paying of dividends on stablecoins lead to a run-off of deposits at traditional financial institutions.
The issue has been a strongly divisive one in Washington, with banks and crypto companies entrenched on opposite sides of the issue of paying of interest on stablecoins, with FIs strongly opposed.
New Powers for Treasury to Help Banks
Under the latest version of the CLARITY Act, Treasury would have the authority to intercede within the first 18 months after the bill is passed in order to provide protections to community banks (those under $10 billion in assets), which are specifically referenced.
In addition, as noted by Jason Stverak, chief advocacy officer with the Defense Credit Union Council (DCUC), the new language also references bank regulators FDIC and OCC, without providing any mention of or deference to NCUA.
So, why, given all the poetical action committee funds and time credit unions have invested on Capitol Hill, in addition to the fact approximately one-third of Americans are reported to belong to credit unions, does the industry continue to not be mentioned in bills that include community banks?
Chasing the Bus
Stverak said there is no simple answer, but one reason is the many members of the House Financial Services Committee and on Senate committee, come from a banking background.
In addition, posited Stverak, banks in the U.S. represent approximately 90% of consumer deposits, which can make it easy to overlook those institutions hold the other 10%.
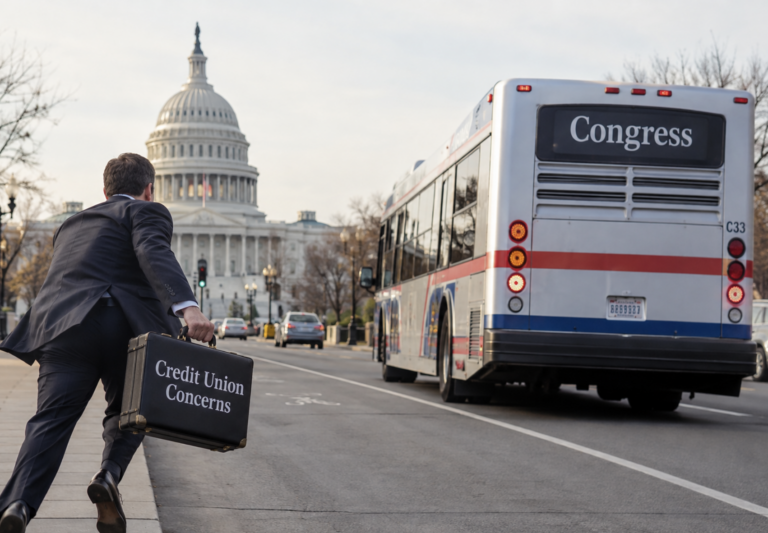
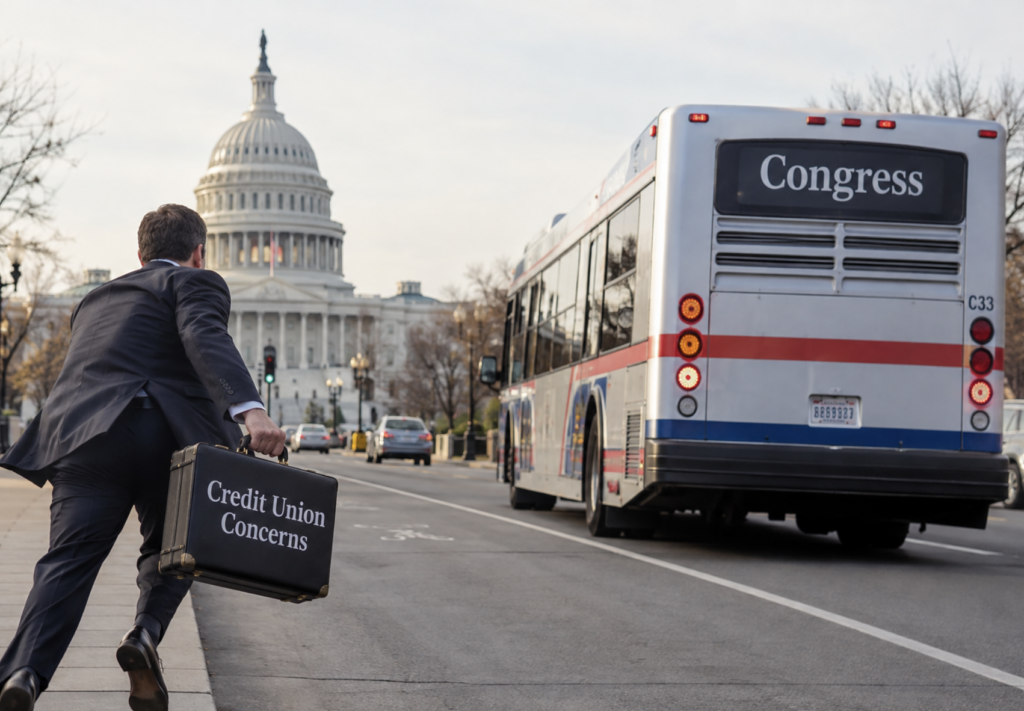
“II think it’s incumbent upon association for credit unions to do a better job of not just knocking on the doors but pounding on the doors and opening them up to ensure that as legislation moves forward or it is being drafted or being considered, that credit unions are at the table and not an afterthought,” said Stverak. “With the millions upon millions of dollars that is used to support candidates, you would hope that we’re not running after the bus as it’s going down the street.”
“The credit union movement has an opportunity to do more to explain its role within the broader financial services system and make sure policymakers understand that credit unions serve a substantial share of Americans, “added Stverak. “The goal should always be to ensure credit unions are part of policy discussions from the beginning, rather than seeking changes after legislation has already been drafted.”