
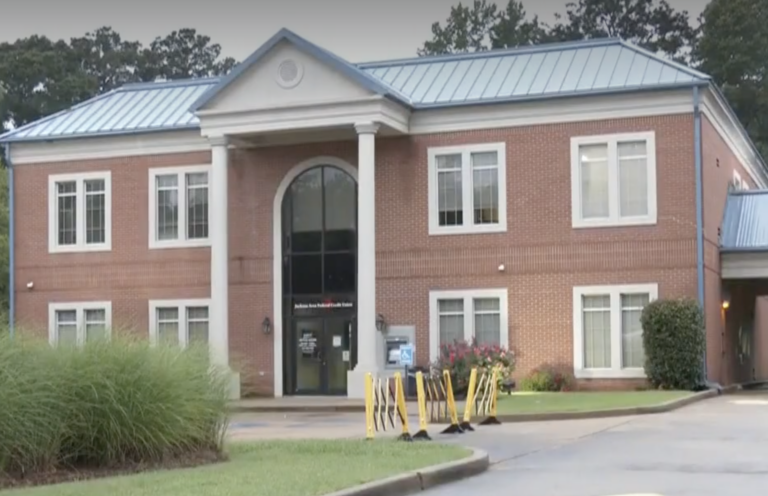
JACKSON, Miss. — The National Credit Union Administration is pressing a federal court to maintain control over retirement funds belonging to the former CEO of the now-liquidated Jackson Area Federal Credit Union and her husband, arguing that even if the accounts are legally protected from seizure, money withdrawn from them would become subject to an existing asset freeze.
As the CU Daily has been reporting, the Jackson Area FCU case involves one of the largest embezzlements in credit union history. NCUA placed the deeply troubled JAFCU into conservatorship in May and has been going through its books ever since. The credit union has since been merged into Alabama-based Five Star Credit Union.
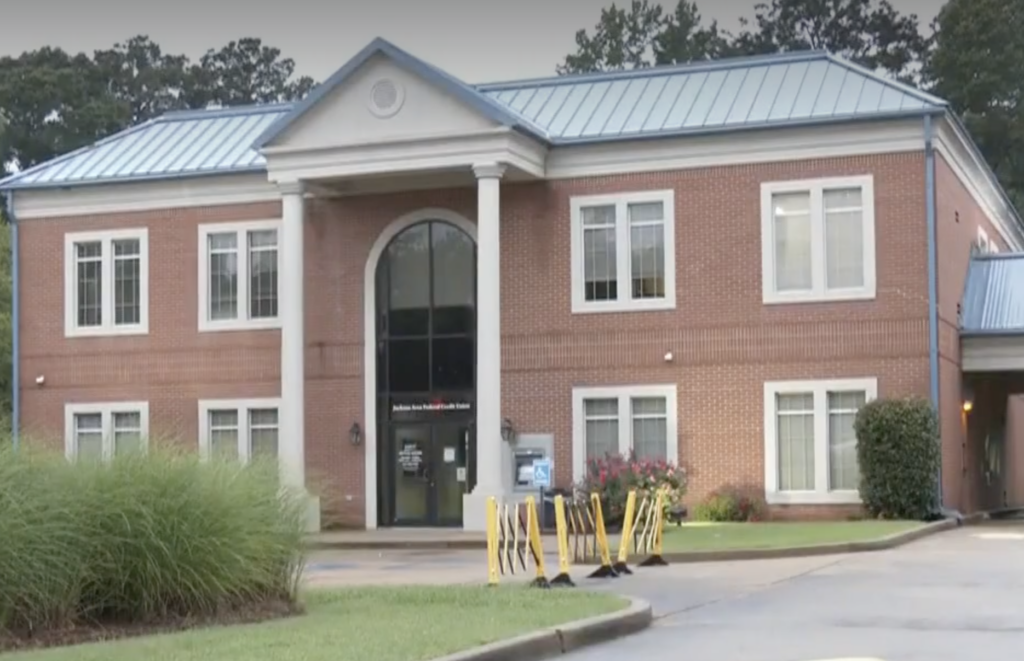
As the CU Daily reported here, former CEO Leigh Bridges pleaded guilty in October to three federal charges stemming from the embezzlement of more than $69 million from the credit union and now faces up to 70 years in prison and millions of dollars in fines when she is sentenced Feb. 25 of 2027. U.S. Magistrate Judge LaKeysha Greer Isaac set Bridges’ bond at $25,000 during a preliminary hearing. Jordan kept the bond in place, allowing Bridges to remain free pending sentencing.
As of its mid-year 5300, JAFCU was reporting $60.8 million in assets, 15,704 members and a whopping $103 million loss and -145.63% net worth. What JAFCU’s ultimate cost will be to the National Credit Union Share Insurance Fund has not yet been determined.
The New Filings
In two filings submitted Nov. 4 in U.S. District Court for the Southern District of Mississippi, the NCUA also asked the court to impose additional requirements before allowing Leigh Bridges, the credit union’s former CEO, and her husband, Chad Bridges, to use frozen funds for living expenses or attorneys’ fees.
A settlement conference held earlier this week did not result in any type of settlement, new court documents also show.
Leigh Bridges has pleaded guilty in connection with the embezzlement at the credit union. The NCUA, acting as the institution’s liquidating agent, is pursuing a separate civil action against the Bridges and Tina Funez.
The latest filings introduce a new legal argument that could complicate Chad Bridges’ efforts to gain access to retirement savings, even if the court determines those accounts are exempt from attachment.
NCUA: Withdrawn Funds Would Be Frozen Again
The Bridges have argued that their retirement accounts contain funds unrelated to the embezzlement and are protected from seizure under Mississippi law.
The NCUA contends that those protections would not necessarily extend to money withdrawn from the accounts.
In its proposed supplemental memorandum, the agency cited federal appellate decisions holding that retirement funds protected under the Employee Retirement Income Security Act, or ERISA, can lose certain protections once distributed to beneficiaries.
The NCUA also argued that Mississippi’s retirement exemption statute protects assets held in retirement accounts or payable to beneficiaries, but does not explicitly protect money already distributed.
According to the agency, even if the court determines the retirement accounts themselves cannot be attached, withdrawals deposited into other accounts belonging to the Bridges would become subject to the preliminary injunction freezing their assets.
The NCUA characterized those funds as becoming “re-frozen” upon withdrawal.
The agency further argued that its statutory authority to attach assets is not necessarily limited to property connected to fraudulent activity.
New Demands for Access to Funds
The NCUA is now asking the court to require additional legal arguments and evidence before permitting either defendant to use frozen money.
Specifically, the agency contends the Bridges should be required to address five factors:
- The likelihood that the NCUA will prevail on its claims.
- Whether defense attorneys knew their fees could be restricted.
- The availability of assets to compensate those harmed.
- Whether the defendants have access to alternative financial resources.
- Whether the amounts requested for legal fees and living expenses are reasonable.
The NCUA argues neither Leigh nor Chad Bridges has adequately addressed those considerations.
Not Addressed in ‘Substance’
The agency also contends neither has demonstrated that releasing frozen funds is necessary to obtain legal representation.
“Neither Leigh nor Chad has addressed any of these factors in substance,” the agency stated in its proposed supplemental memorandum.
The NCUA wants the court to require new motions addressing those issues, giving the agency an opportunity to respond before any money is released.
Agency Seeks Permission to Introduce New Arguments
In a separate filing, the NCUA requested permission to submit the supplemental memorandum after its earlier responses to the Bridges’ motions.
The agency acknowledged that its attorneys had not fully developed the new arguments until conducting legal research in preparation for a court-ordered settlement conference.
It argued that addressing the issues now could avoid unnecessary litigation over whether federal law permits attachment of retirement accounts.
The NCUA also said it would not object if the Bridges were permitted to file responses to the supplemental arguments.
The filings do not establish that the court has accepted the agency’s new legal position or authorized additional restrictions.
The dispute remains centered on whether the Bridges can access retirement savings and other frozen assets while the NCUA pursues recovery in connection with the credit union’s failure.