

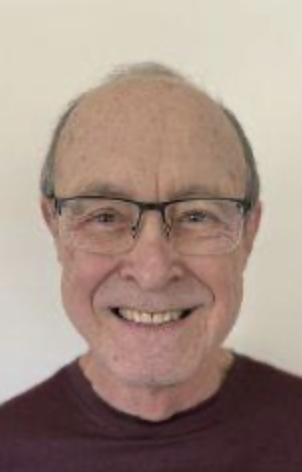
SACRAMENTO, Calif.–Dr. Scott Rose, who has been active in publicly opposing the proposed merger between Sacramento, Calif.-based SAFE Credit Union and Seattle-based BECU, is continuing his efforts to rally SAFE members to vote against the combination now that voting is officially underway.
Rose had a letter to the editor published in six Central California news publications—the Folsom Telegraph, Roseville Press Tribune, Placer Herald (Rocklin), Lincoln News-Messenger, Loomis News and Auburn Journal—in which he raised numerous objections to the combination.
As the CU Daily has been reporting, as of mid-year, SAFE CU, founded in 1940, had $4.417 billion in assets and 246,000 members. SAFE CU reported $21.39 million in net income as of mid-year, with net worth of 10.82%. The $29.62-billion BECU, which was founded in 1935 and which has 1.59 million members, had $86.1 million in net income at mid-year, with net worth of 12.57%.
Breaking Down the Payouts
“On Aug. 26, the National Credit Union Association (NCUA), the federal agency that insures member deposits at credit unions, posted on its website its authorization for the SAFE Credit Union acquisition by Boeing Employees Credit Union,” the letter states. “Included in this online posting, the NCUA reported the following information regarding executive compensation for the top five leadership posts at SAFE.
“The total amount that these five individuals will receive when this deal closes is $14.56 million. The following is a breakdown of this sum,” the letter continues, adding that the payments include:
- Chief Executive Officer Faye Nabhani to be paid $4.353 million.
- Chief Operating Officer Tiffani Vargas to be paid $3.54 million.
- Chief Financial Officer Alexis Fitzpatrick to be paid $2.768 million.
- Chief Technology Officer Michael McCarthy to be paid $2.088 million.
- Chief Human Resources Officer Colleen Nerius to be paid $1.797 million.
‘Astonishing Payout’
“This is an astonishing payout coming from a not-for-profit financial cooperative owned by its members!
In addition to the money being paid to the top SAFE five executives, all costs of this transaction will be borne by SAFE Credit Union and paid out of the current member equity,” the letter continues. “And when the deal closes, all $419,000,000 of member-owner money will be handed over to Boeing Employees Credit Union.
“Based upon information submitted by SAFE, the NCUA reported total SAFE assets of $4.417 billion, including $3.937 billion in member deposits. SAFE also reported current member equity totaling $419 million. This is money that belongs to all SAFE members. With a current membership base of more than 245,000, each individual member owns and is entitled to, a payout of approximately $1700 per person.
‘Imperative’ Members be Compensated
“It is imperative that members are compensated for what is rightfully theirs.
“And you can be certain that SAFE members are in the best position to determine for themselves how to use the $1700 per person payout to which they are entitled,” Rose’s letter goes on to state. “According to the NCUA, SAFE has a low income designation (LID). This means that more than 50 percent of members have family incomes that are 80 percent or less than the medium income for our region. An NCUA LID designation allows access to funding that expands service to lower income members such as credit builder loans, payday alternative short-term loans, affordable home loans, hardship fee waivers, and loan deferral programs. Although not the most profitable products, these serve an important mission. Boeing Employees Credit Union does not have this designation.
An ‘End-Around’
“However the most important fact is that the SAFE board intends to do an end run around the statutory requirement that a majority of members must approve the merger by asking for an exception. This is the actual ballot wording:
“(T)his is to advise you that the Board of Directors will make an application under California Financial Code Section 15201(b) for approval of the merger in the event that a majority of all members of SAFE do not vote to approve the merger, in person at the meeting, or by mail-in or online ballot.”
“Chip Filson, a nationally known credit union expert and opinion writer has stated: “SAFE’s leadership does not want to even try to get the majority of members to vote because that would require a PR campaign and open dialogue,” the letter continues. “That would give members and the community a chance to learn the full facts of what this sellout will cost them.” Filson adds, “the pretense… of instant democracy by a board that had no contested elections in recent memory just compounds this financial farce.
‘Take a Stance’
“I am urging the leaders of our community to take a stance in opposition to this transaction. If SAFE Credit Union ceases to exist, the Sacramento region will face severe adverse economic consequences,” the letter concludes, noting Rose has been a member of SAFE Credit Union since 2002.
The CU Daily has coverage of the merger and SAFE CU’s message to members here.





4 Responses
Kudos to Scott Rose for taking a stand – these enormous manager payouts clearly introduce a financial conflict of interest. This is so crazy.
The management pay is not a conflict of interest. Bad financial stewardship perhaps, but not a conflict of interest in any formal or legal context. There are far bigger issues with this merger anyways.
Above comment was mine
John Tippets
Retired Credit Union CEO
Leadership principles include; Trust,Stewardship, Integrity and more .. In a Credit Union the mission is to improve the welfare of the members.
All of the above seem to e ignored in this proposal….