
BUCKSPORT, Maine —One credit union CEO has announced retirement plans, while another CU has named a new president and CEO.
In Maine, Seaboard Federal Credit Union President and CEO Kyle Casburn has announced plans to retire May 31, 2027, after more than three decades leading the institution.
Casburn joined Seaboard in March 1995. During his tenure, the credit union grew from $42 million in assets to $248 million as of September 2026, according to the statement.
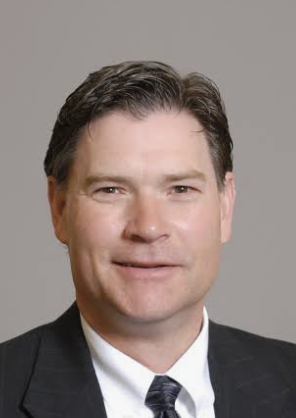
Seaboard said Casburn guided the institution through digital transformations, two community charter conversions and significant economic disruptions, including the Y2K transition, the Great Recession, the Bucksport paper mill closure and the COVID-19 pandemic.
“Serving as CEO for the past 31 years has been the greatest honor of my professional life,” Casburn said in a statement. “When I first joined, our goals were simple: to improve operations while providing our members with financial benefits and security. I am incredibly proud of how we stayed true to that mission while navigating a changing financial landscape. The heart and soul of this credit union has always been its people, and I am profoundly grateful to our board and dedicated staff for their support.”
Search For A Successor
Seaboard’s board has selected Shanley Search Partners to evaluate internal and external candidates to succeed Casburn, a step the credit union said is intended to ensure institutional stability and continuity.
“Kyle played a pivotal role in shaping Seaboard Federal Credit Union into the strong, resilient organization it is today,” Board Chairman Tony Manzo said in a statement.. “His leadership, integrity, and unwavering commitment to our employees and members have positioned us for long-term success. On behalf of the Board, our employees, and our members, we are deeply grateful for Kyle’s decades of outstanding service and look forward to working with him to create a seamless transition.”
New CEO Named at St. Mary’s CU
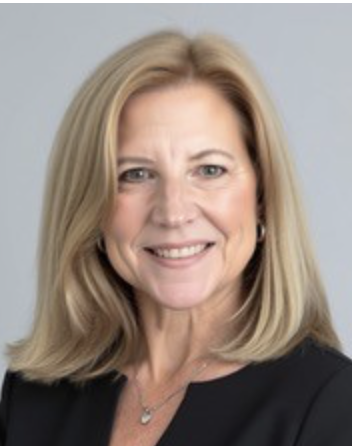
Separately, in Marlborough, Mass., the $1.025-billion St. Mary’s Credit Union has named Brenda Diepold as its next president and CEO, effective Oct 5.
SMCU also announced that longtime executive Jim Petkewich will be retiring in February 2027 and remain with the institution as a special advisor to the CEO and board as SMCU completes its current merger conversion with the $147-million MetroWest Community Federal Credit Union.
“I want to thank Jim Petkewich for his more than 20 years of exceptional leadership and service to not only St. Mary’s Credit Union but to the entire MetroWest community,” Board Chair Brian Bouvier said in a statement. “Jim’s leadership and deep knowledge of this organization was critical to successfully completing our merger with MetroWest this past summer. As we looked towards SMCU’s future, our priority was finding a proven leader to provide long-term stability and guide St. Mary’s Credit Union through its next chapter of growth. We found that leader in Brenda. Her experience, vision and deep understanding of community banking make her exceptionally well suited to lead St. Mary’s Credit Union forward.”
More Than 30 Years’ Experience
Diepold brings 32 years of experience to SMCU, including the last eight in senior leadership roles for HarborOne Bank in Brockton, Mass. Most recently, she has served as executive vice president and chief banking officer of the $5.7 billion institution for the last three years.
Prior to her time with HarborOne Bank, Diepold held leadership positions at Fleet Bank, Sovereign Bank, Santander Bank, and Century Bank, building extensive experience in strategic growth, organizational transformation and customer-focused financial services.
The Dedham, Mass. resident and University of Rhode Island alumna will lead SMCU into its next chapter of growth, with a focus on strengthening the credit union’s longstanding commitment to its members, employees and the MetroWest communities it serves, SMCU said.
Honored to Have Opportunity
“I am honored to have the opportunity to lead St. Mary’s Credit Union and join an organization with such a strong history of serving its members and the MetroWest community,” said Diepold said in a statement. “Brian, Jim, and the entire SMCU team have built a strong foundation rooted in service, trust, and financial strength. I’m looking forward to working alongside our employees to build on that legacy and ensure St. Mary’s continues to grow for generations to come.”
44 Years in Banking
Petkewich, a more than 20-year veteran of St. Mary’s Credit Union who has spent 44 years in banking, assumed the role of president and CEO in May, “despite having previously planned to retire, to provide experienced leadership and continuity during an important period for the organization,” SMCU said. “Under his leadership, SMCU successfully completed its merger with MetroWest Community Federal Credit Union in July. With the merger complete and the credit union positioned for its next phase of growth.”
Petkewich will help ensure a seamless transition to Diepold before retiring in February, the credit union added.
“It has been my absolute honor to be part of St. Mary’s Credit Union and serve the MetroWest community for more than 20 years, and I am incredibly proud of everything we’ve accomplished during that time,” Petkewich said in a statement. “SMCU is a special place deeply rooted in community and helping people reach their personal and financial goals. I believe that the institution will continue to best serve people throughout the region under the leadership of Brian and Brenda and the countless others who make up the fabric of SMCU.”