
DUBLIN, Ireland — Credit unions around the world operate under widely different business models, but institutions across markets are confronting many of the same pressures, including rising regulatory demands, escalating technology costs, increased competition and the need to generate enough surplus to invest in their future, according to new research from the Swoboda Research Centre.
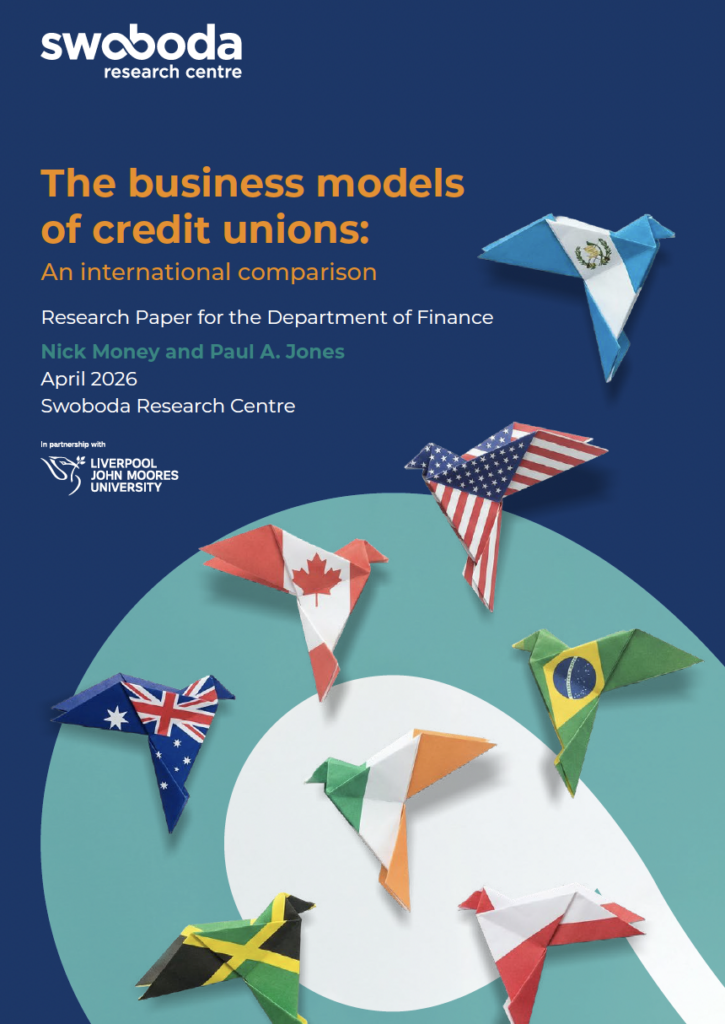
The research, “The Business Models of Credit Unions: An International Comparison,” by Nick Money and Paul A. Jones, examines credit union systems across different income levels, regulatory structures and cooperative traditions. It was commissioned by Ireland’s Department of Finance, although the centre said the analysis and conclusions are those of the authors.
The study is intended in part to inform decisions facing Ireland’s credit union sector as institutions confront pressure to consolidate and modernize. But its international findings also highlight broader questions about how cooperative financial institutions create value, deliver it to members and retain the financial resources necessary to remain viable.
Different Models, Common Pressures
The Swoboda Centre–which was cofounded by former CUNA President Ralph Swoboda after he left the organization and became active in working with Ireland’s credit unions– said there is no single international model for credit unions. Business models are shaped by national income, regulation and the historical development of the cooperative sector.
Despite those differences, credit unions across jurisdictions face four common pressures:
- Regulation: Regulatory frameworks are becoming increasingly bank-like, raising compliance expectations.
- Technology: Digitalization costs continue to increase as institutions attempt to meet changing member expectations.
- Competition: Credit unions face pressure from both for-profit banks and more agile nonbank lenders.
- Investment: Institutions must generate sufficient surplus to reinvest in their long-term capabilities.
The research organizes its international analysis around three areas — value creation, value delivery and value capture.
Value Creation: What Purpose Does the Credit Union Serve?
Cooperative ownership is the common thread among credit unions internationally, but the purpose that ownership serves varies substantially by country, according to the research.
The Swoboda Centre identified three broad approaches:
- The Inclusion Mandate: In middle-income countries such as Brazil, Guatemala and Jamaica, credit unions explicitly serve a financial inclusion role, including providing services to rural communities, informal workers and other underserved populations.
- The Retail Competitor: In higher-income markets such as Canada, the United States and Australia, where banking exclusion is relatively low, credit unions largely operate as mainstream retail financial institutions. They compete directly with banks through pricing, trust and community presence.
- The Hybrid Approach: The United States combines a highly developed mainstream retail credit union sector with a sophisticated community development sector focused specifically on addressing financial exclusion.
The study said the critical distinction among the models is not necessarily the products credit unions offer but their underlying purpose.
The question, according to the researchers, is whether cooperative ownership actively determines how financial services are integrated and delivered or whether it primarily serves as the legal ownership structure behind what otherwise resembles a conventional retail financial institution.
Value Delivery: Three Ways to Build Scale
The research also examined how credit union systems organize themselves to achieve scale and manage risk, identifying three structural models.
In federated and integrated systems, functions such as information technology, liquidity, branding and risk management are centralized and mandatory. That approach can produce significant economies of scale and give the system greater ability to make collective investments. The research cites Desjardins in Quebec as an example.
Coordinated systems have strong central oversight while allowing individual credit unions to retain local autonomy.
At the other end of the spectrum are decentralized systems, characterized by significant institutional independence and voluntary cooperation. While that structure helps preserve local identity, the researchers said it can make it significantly more difficult to finance technology investments and absorb increasing regulatory costs.
Where the Money Goes Matters
The third component, value capture, examines how credit union systems use the financial value they generate.
Unlike investor-owned institutions, credit unions across the jurisdictions studied ultimately capture value for members rather than outside investors. But the mechanisms for doing that differ sharply depending on organizational structure, the research found.
Federated systems can retain surplus at the system level and use those resources to finance shared infrastructure and strengthen long-term resilience.
Decentralized systems, by comparison, rely primarily on retained earnings at individual institutions.
Those structural differences become particularly significant as technology and regulatory requirements demand investments that may be difficult for individual institutions to make on their own.
Ireland Faces Autonomy vs. Integration Question
For Ireland, the research concludes that the central strategic tension is between autonomy and integration and between tradition and evolution.
The international evidence does not point to one model that Ireland should adopt, the researchers said. Instead, experience across countries shows that scale, capital strength, technological capability and strategic clarity repeatedly emerge as important determinants of long-term viability.
Irish credit unions are individually well-capitalized, with sector capital ratios significantly above regulatory minimums. The challenge, according to the study, is that the capital is spread among autonomous institutions.
That fragmentation limits the industry’s collective ability to finance shared infrastructure at a time when an increasingly bank-like regulatory environment is likely to require greater investment, the researchers said.
Ireland Sits Between International Models
The researchers found Ireland does not fit neatly into any of the international models studied.
Its credit unions have a narrower range of products than institutions in many other upper-middle- and high-income countries, while retaining a strong commitment to community, social purpose and local autonomy.
Determining the future role credit unions should play in Irish society is therefore critical to deciding which international lessons are most applicable, the report said. If value creation defines whom credit unions serve and what they provide, the structures used for value delivery and value capture should follow from that purpose.
Ultimately, the Swoboda Centre said the issue facing Irish credit unions is no longer whether the sector needs to change.
“The question is not whether change is required, but how deliberately and collectively that change is shaped,” the research said.
For the full report, go here.